 USD
 GBP
 CNY
 EUR
 INR
 JPY
 MYR
 ZAR
 KRW
 THB


Growth Opportunities in the Chinese Fuel Additives Market
Focus Products—Lubricity Improvers and Cold Flow Additives for Diesel
13-Nov-2017
Asia Pacific
Market Research
P9CD-01-00-00-00
CM01512-AP-MT_21109
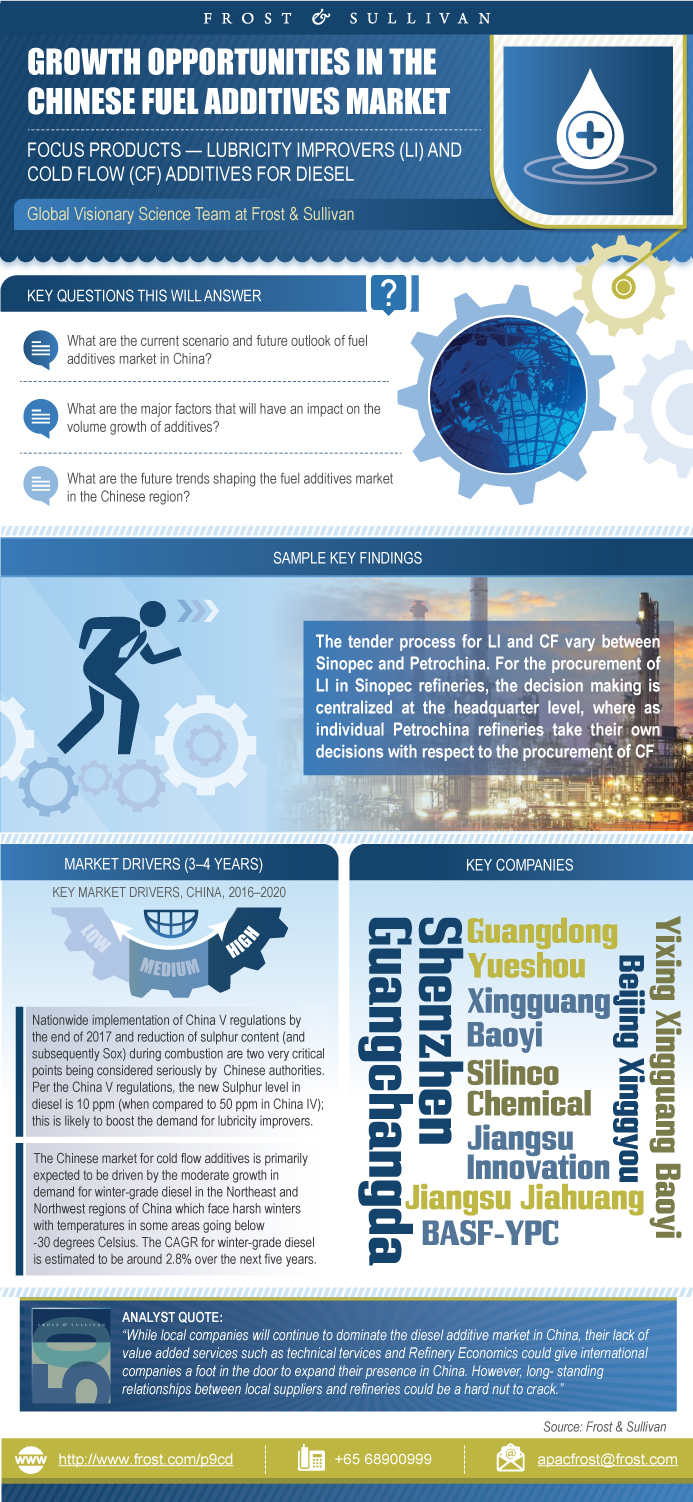
The Chinese diesel market is set to grow at a robust pace over the next 5 to 7 seven years as production of diesel vehicles increases and the introduction of China V specifications takes center stage. The implementation of China V regulations is key to the consumption of diesel, and in turn, lubricity improvers (LI) and cold flow (CF) additives. Lubricity improvers are estimated to grow at a strong CAGR of 11.9% between 2016 and 2022 while cold flow additives, which are predominantly used in winter diesel, will grow at a lower CAGR of 2.8%. Excess kerosene availability in China will also be a challenge for the growth of cold flow additives, as it is a cheap alternative. Local players in China currently dominate the supply of LI and CF additives to Sinopec and Petrochina.
The local players that dominate the market have excellent relationships with both Sinopec and Petrochina. These relationships are long-standing ones which gives them an edge over new entrants. New companies trying to tap opportunities in the LI and CF market in China are advised to partner with the domestic players, as it will enable them to get a ‘ foot in the door’ with the state-owned enterprises. Owing to these long-standing relationships, the technical specifications set by the refineries are published in such a way that most of these domestic players will qualify. International additive companies have superior technical specifications as compared to domestic players, but these improved specifications are often perceived as premium or expensive.
The procurement process for LI and CF is different between Sinopec and Petrochina. While Sinopec is predominantly a consumer of LI, Petrochina is a large consumer of CF, as Petrochina produces larger quantities of winter-grade diesel due to its locations in colder regions across China. While the procurement process for Sinopec is done completely at the headquarter level, the process for the procurement of CF is left to individual Petrochina refineries. This difference in the tender processes has made domestic additive manufacturers increase their sales and marketing staff in order to have a constant presence at the location of various refineries.
There are however interesting ways by which international LI and CF players can enter the China market and be successful. One of them is to partner with a strong domestic additive manufacturer. The other option is to provide value-added services such as refinery economics exercises, training workshops for refinery personnel on the advantages of using CF over kerosene as well as joint R&D exercises. These services will go a long way in building relationships with refineries, which is the cornerstone of success in the diesel additive market in China.
Key Findings
LI & CF Market Information Snapshot
Macroeconomic Outlook
Diesel and Kerosene Production and Consumption
LI Market Outlook
LI Value Chain Analysis
LI Typical Route to Market
Top LI Manufacturers in China
Refinery Procurement Practices
CF Market Outlook
CF Value Chain Analysis
CF Typical Route to Market
Top CF Manufacturers in China
CF Procurement Process
China V Implementation Impact
Emission Limits for China V
Incentives for Refineries to switch to China V
China Refining Capacity
Refinery Utilization Trends
China V Implementation Map
Diesel Outlook—Refining Capacity
Diesel Outlook—Backward Capacity Elimination
Winter Diesel Outlook
Other Demand Drivers for Diesel
Aviation Kerosene
PetroChina Diesel and Kerosene Outlook, 2016 to 2020
China Refinery Expansion Plans
China Refinery Expansion Plans
LI Market in China
Key Drivers for the LI Market in China
Key Challenges for the LI Market in China
Market Outlook for LI—Conditions for Ester Adoption
Market Share Analysis per LI Type
Distributor Criteria for Selecting a LI Manufacturer
Value Chain Analysis
Value Chain Analysis for LI Additives in China
Raw Material Analysis
Alternative Raw Materials for Lubricity Improvers
TOFA Imports into China
Typical Route to Market
Refinery Procurement Practices
Supplier Selection Criteria—Refinery Viewpoint
Supplier Selection Criteria—Manufacturer Viewpoint
Acid vs. Ester Product Awareness—Refineries
Ester-based LI Adoption
Top 5 LI Manufacturers
Local LI Manufacturer Capabilities
Market Outlook
Winter Diesel and Usage of Cold Flow Additives
Key Drivers for the CF Market in China
Key Challenges for the CF Market in China
Key Takeaways from China’s 13th Five-Year Plan
Refinery Configuration—Hydrocracking Capacities
Distributor Criteria for Selecting a Manufacturer of CF
Value Chain Analysis
Import of Aviation Kerosene by Country
Cold Flow—Typical Route to Market
Cold Flow—Procurement Process
Supplier Selection Criteria—Refinery Requirement
Product Awareness—Refineries
Top CF Manufacturers in China
Porter’s 5 Forces Analysis for the LI Market
Opportunity for Emerging Players and Industry Threat
Porter’s 5 Forces Analysis for the CF Market
Opportunity for Emerging Players and Threats
Growth Opportunity
Strategic Imperatives for Success and Growth
3 Key Takeaways
Legal Disclaimer
Definitions and Abbreviations
Learn More—Next Steps
 List of Figures
- 1. Fuel Additives Market: LI & CF Snapshot, China, 2017
- 2. Fuel Additives Market: Top 5 Manufacturers, China, 2017
- 3. Fuel Additives Market: Top 5 CF Manufacturers, China, 2017
- 4. Fuel Additives Market: Diesel Fuel Quality Roadmap, China, 2017
- 5. Fuel Additives Market: Emission Limit by Vehicle Type, China 2017
- 6. Fuel Additives Market: Implementation Timeline of Fuel Standards by Region, China, 2017
- 7. Fuel Additives Market: PetroChina Diesel and Kerosene Outlook, China, 2016–2020
- 8. Fuel Additives Market: Refinery Expansion Plans, China, 2017
- 9. LI Segment: Drivers, China, 2016–2020
- 10. LI Segment: Challenges, China, 2016–2020
- 11. LI Segment: Distributor Criteria for Selecting a Manufacturer, China 2017
- 12. LI Segment: TOFA Imports, China, 2017
- 13. LI Segment: Supplier Selection Criteria of Refineries, China, 2017
- 14. LI Segment: Supplier Selection Criteria of Manufacturers, China, 2017
- 15. LI Segment: Top 5 Manufacturers, China, 2017
- 16. CF Segment: Drivers, China, 2016–2020
- 17. CF Segment: Challenges, China, 2016–2020
- 18. CF Segment: Hydrocracking Capacity of Refineries, China, 2017
- 19. CF Segment: Distributor Criteria for Selecting a CF Manufacturer, China, 2017
- 20. CF Segment: Aviation Kerosene Import Breakdown by Select Country, Global, 2011–2017
- 21. CF Segment: Supplier Selection Criteria of Refineries, China, 2017
- 22. CF Segment: Top 5 Manufacturers, China, 2017
 List of Charts
- 1. Macroeconomic Growth Outlook, China, 2015–2020
- 2. Diesel Production and Consumption Forecast, China, 2015–2020
- 3. Kerosene Production and Consumption Forecast, China, 2015–2020
- 4. Lubricity Improver Demand, China, 2015–2020
- 5. Fuel Additives Market: LI Value Chain, China, 2017
- 6. Fuel Additives Market: LI Route to Market, China, 2017
- 7. Cold Flow Demand, China, 2015–2020
- 8. Fuel Additives Market: CF Value Chain, China, 2017
- 9. Fuel Additives Market: CF Route to Market, China, 2017
- 10. Fuel Additives Market: CF Procurement Process, China, 2017
- 11. Number of Refineries*, China, 2015
- 12. Refinery Utilization Trend, China, 2010–2015
- 13. Diesel Production—Scenario 1, China, 2015–2020
- 14. Diesel Production—Scenario 2, China, 2015–2020
- 15. Winter Diesel Outlook, China, 2016–2020
- 16. Heavy Commercial Vehicle Outlook, China, 2015–2020
- 17. Aviation Kerosene Imports, China, 2011 to 2015
- 18. LI Segment: Base Case Scenario, China, 2015–2020
- 19. LI Segment: Demand* Forecast, China, 2015–2020
- 20. LI Segment: Market Share by LI Type, China, 2015, 2017, and 2020
- 21. LI Segment: Value Chain, China, 2017
- 22. LI Segment: Route to Market, China, 2017
- 23. CF Segment: Demand Forecast, China, 2015–2020
- 24. CF Segment: Value Chain, China, 2017
- 25. CF Segment: Route to Market, China, 2017
- 26. CF Segment: Procurement Process, China, 2017
Speak directly with our analytics experts for tailored recommendations.
Recent related Performance Materials research
30 Oct 2026 | Global | Technology Research
Innovations in Nanotechnology Spanning Functional, Sustainable Nanomaterials, Nanoscale Energy Storage, Molecular Sensing, Catalysis, and Nanofiber Engineering
This issue of the Nanotechnology Opportunity Engine profiles significant advances in nanotechnology for various industrial applications. The featured innovations include Nanolayered Polymer Films for High-Performance Functional Applications, Graphene Dispersions for High-performance Protective Coati...
29 Oct 2026 | Global | Market Research
Materials for Data Centers, Global, 2026–2032
The rapid expansion of AI, cloud computing, and high-performance computing is changing the way data centers are designed and operated. Higher computing power and increasing rack densities are creating greater requirements for heat management, power efficiency, reliability, and infrastructure perform...
26 Oct 2026 | Global | Market Research
Polymeric Membrane Market, Global, 2025–2032
Polymeric membranes play a critical role in modern filtration and separation processes, enabling efficient contaminant removal in water treatment, wastewater management, industrial processing, and medical applications. These materials act as selective barriers that ensure purity, safety, and process...
16 Oct 2026 | Global | Technology Research
Innovations in Surface Technologies for Medical Devices, Battery Components, Sustainable Packaging, Self-Cleaning Facades, Thermal Sprays, and others
This edition of the Advanced Coating & Surface Technology Opportunity Engine profiles significant advances in advanced coatings and surface treatments for various industrial applications. The featured innovations include Automated High-speed Coating and UV-cure Solutions, Water-based Functional Alum...
12 Oct 2026 | Global | Market Research
High-Performance Polymers Industry, Global, 2025–2032
High-performance polymers (HPPs) represent the most advanced class of engineering plastics. They are designed to deliver exceptional performance in environments where conventional plastics and metals are unable to meet stringent operating requirements. These materials exhibit outstanding thermal sta...
Purchase includes:
- Report download
- Growth Dialog™ with our experts
Growth Dialog™
A tailored session with you where we identify the:- Strategic Imperatives
- Growth Opportunities
- Best Practices
- Companies to Action
Impacting your company's future growth potential.