 USD
 GBP
 CNY
 EUR
 INR
 JPY
 MYR
 ZAR
 KRW
 THB


Smart Building Solutions, Global, 2025–2031
AI-Driven Unified Building Intelligence Enabling the Shift to Autonomous Building Operations
27-Aug-2026
Global
Market Research
PLWE-01-00-00-00
EN_2026_34850
Key Takeaways: Smart Building Solutions Market
- The Smart Building Solutions Market is transitioning from hardware-led building automation toward integrated, AI-enabled and platform-centric building operations.
- The global market was valued at approximately $20,045.8 million in 2025 and is forecast to reach $41,070.1 million by 2031.
- The market is projected to expand at a 12.7% CAGR from 2025 to 2031, supported by decarbonization, energy efficiency, AI, and predictive operations.
- Energy efficiency, operational efficiency, and occupant comfort and safety represent the three strategic pillars of the market.
- IoT sensors, edge computing, cloud platforms, AI, and connected building-management technologies are enabling real-time monitoring and autonomous decision-making.
- Commercial, industrial, education, healthcare, and data-center buildings are major end-user segments, with additional opportunities across government, transportation, sports, cultural, and residential buildings.
- The Smart Building Market remains fragmented, with more than 350 competitors generating over $5 million in revenue; the top four competitors accounted for 74.4% of 2025 revenue.
- Growth opportunities increasingly extend to small and medium-sized buildings through subscription-based platforms, partner ecosystems, remote management, and low-friction deployment models.
Report Summary: Smart Building Solutions Market
The Smart Building Solutions Market encompasses integrated hardware, software, and digital services designed to automate, optimize, and intelligently manage commercial, educational, healthcare, industrial, data-center, and other building environments. The market combines automation controllers, edge and IoT gateways, cloud-based and on-premises platforms, building-management systems, energy-management solutions, analytics, and associated digital services.
The provided Frost & Sullivan research identifies three strategic pillars shaping the Smart Building Market: energy efficiency, operational efficiency, and occupant comfort and safety. Energy efficiency is supported by building energy-management systems and sustainability-management solutions, while operational efficiency is enabled through digitized asset maintenance and asset-management platforms. Occupant-focused solutions combine workplace experience, IoT, AI, space intelligence, and safety and security management.
The market was valued at approximately $20.05 billion in 2025 and is forecast to grow at a 12.7% CAGR through 2031, reaching approximately $41.07 billion. Growth is supported by enterprise decarbonization mandates, increasing energy costs, AI-driven building intelligence, IoT proliferation, and the transition from reactive facility management toward predictive and increasingly autonomous building operations.
Analyst's Words: Smart Building Solutions Market
Anirudh Bhaskaran, Lead Analyst, Smart Building Solutions Market
“The Smart Building Solutions Market is at a pivotal inflection point, transitioning from a hardware-driven, project-based industry toward an AI-native, platform-centric ecosystem where autonomous operations, recurring software revenue, and ecosystem scale increasingly shape competitive positioning.”
Top 3 Growth Perspectives
- AI-enabled autonomous operations: AI agents capable of closing operational control loops without human intervention are becoming an increasingly important expectation for enterprise buyers evaluating new smart-building platform investments.
- Large untapped building base: Millions of non-automated small and medium-sized commercial buildings represent a substantial volume opportunity. Low-friction deployment, subscription-based models, and clearly demonstrated outcomes can support broader adoption.
- Ecosystem-led distribution: Direct sales alone cannot effectively reach the large number of buildings within the total addressable market. Partner ecosystems can provide scalable distribution and create compounding value as smart-building platforms expand.
Market Overview & Trends: Smart Building Solutions Market
The Smart Building Solutions Market is undergoing a structural transformation as buildings evolve from passive physical assets into connected, responsive, and increasingly autonomous environments. Traditional building-management approaches are being supplemented by IoT sensors, edge computing, cloud platforms, artificial intelligence, analytics, and digitized asset-management technologies.
One of the most important trends is the movement toward AI-driven building intelligence. AI can process data generated by connected building assets and support real-time operational decisions, predictive maintenance, energy optimization, and occupant-focused services. This is shifting the Smart Building Market from reactive facility management toward predictive and data-driven operations.
Energy efficiency and sustainability are also major market influences. Rising energy costs, enterprise decarbonization objectives, building-energy requirements, and sustainability initiatives are encouraging organizations to adopt building energy-management systems and sustainability-management platforms. AI-driven HVAC optimization and intelligent energy management can contribute to more efficient building operations.
Another important trend is the proliferation of IoT sensors, edge devices, and cloud-based analytics. These technologies enable real-time monitoring and centralized management across distributed building portfolios. The combination of cloud platforms and 5G connectivity can further support remote management and scalable deployment.
The market is also expanding beyond large enterprise buildings. Millions of small and medium-sized commercial buildings remain less automated, creating opportunities for subscription-based platforms, simplified deployment, and partner-led distribution. The Smart Building Market is therefore increasingly shaped by scalability and ecosystem development in addition to individual building projects.
Scope of Analysis: Smart Building Solutions Market
The scope of the Smart Building Solutions Market covers integrated hardware, software, and associated digital services used to automate, optimize, and intelligently manage building environments. Hardware includes automation controllers, edge devices, and IoT gateways. Software includes cloud-based and on-premises platforms supporting building-management systems, energy management, and analytics.
Associated digital services include software installation, configuration, troubleshooting, remote maintenance, training, and data-driven advisory services. Field-level devices and traditional field installation or repair services are excluded from the market definition. Hardware, software, and associated digital services are not separately segmented where they are predominantly delivered as integrated smart-building solutions.
Frost & Sullivan structures the market around three strategic pillars: Energy Efficiency, Operational Efficiency, and Occupant Comfort & Safety. Energy efficiency incorporates advanced building energy-management systems and sustainability management. Operational efficiency includes digitized asset maintenance and asset-management platforms. Occupant comfort and safety incorporates workplace experience, space and occupancy intelligence, and safety and security management.
The study covers 2022–2031, with 2025 as the base year and 2026–2031 as the forecast period. Geographic coverage includes North America, Europe, Asia-Pacific, and Rest of the World. End-user verticals include commercial, industrial, healthcare, education, data centers, and others.
Market Segmentation Analysis: Smart Building Solutions Market
The Smart Building Solutions Market is segmented primarily by end-user industry vertical. The study identifies commercial, industrial, education, healthcare, data centers, and other buildings as key segments.
Commercial
The commercial segment includes office, retail, and hospitality buildings. These facilities can benefit from integrated building-management, energy optimization, occupancy intelligence, maintenance management, and workplace-experience solutions. Commercial buildings represent an important opportunity for providers seeking to combine operational efficiency with occupant experience.
Industrial
The industrial segment includes process and discrete industries. Smart building technologies can support operational visibility, energy management, asset maintenance, and connected facility operations across industrial environments.
Education
The education segment includes high schools and university campuses. Campus environments can use smart-building platforms to coordinate energy consumption, building operations, security, occupancy, and facility management across multiple buildings.
Healthcare
Healthcare includes hospitals, healthcare centers, clinics, and research laboratories. These environments have complex operational requirements, making integrated building intelligence relevant to energy management, asset management, safety, security, and occupant conditions.
Data Centers
The data-center segment includes colocation facilities, hyperscale data centers, and enterprise data centers. Energy efficiency, reliability, asset monitoring, environmental management, and predictive maintenance are particularly important within these high-intensity facilities.
Others
The others segment includes high-rise residential buildings, government buildings, airports, sports complexes, cultural buildings, and industrial warehouses. These applications expand the addressable opportunity for the Smart Building Market beyond conventional commercial facilities.
From a solution perspective, the market is also structured around energy efficiency, operational efficiency, and occupant comfort and safety. The convergence of these areas is increasing demand for unified platforms capable of collecting and analyzing building data while enabling real-time or automated responses.
Revenue & Spending Forecast: Smart Building Solutions Market
The global Smart Building Solutions Market generated approximately $20,045.8 million in revenue in 2025. Frost & Sullivan forecasts the market to expand at a 12.7% CAGR between 2025 and 2031, reaching approximately $41,070.1 million by 2031.
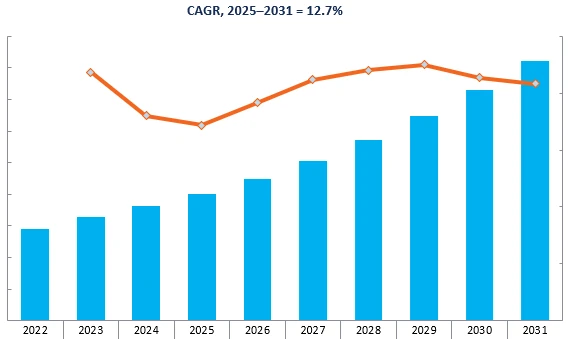
The forecast indicates sustained annual expansion. Revenue is estimated at approximately $22,351.0 million in 2026, rising to $25,189.6 million in 2027 and $28,514.6 million in 2028. The market is projected to reach approximately $32,364.1 million in 2029, $36,506.7 million in 2030, and $41,070.1 million in 2031.
The growth trajectory reflects increasing investment in intelligent building platforms, energy management, connected assets, predictive maintenance, AI-driven automation, and occupant-focused technologies. The transition from reactive facility management toward predictive and autonomous operations is expected to support software and digital-service opportunities alongside traditional hardware deployments.
The Smart Building Market is also expected to benefit from the expansion of cloud-based platforms and remote management models, particularly as providers target distributed building portfolios and smaller commercial facilities.
Growth Drivers: Smart Building Solutions Market
Several structural factors are supporting expansion of the Smart Building Solutions Market.
Energy efficiency and sustainability: Increasing demand for energy efficiency is accelerating adoption of smart building technologies. AI-driven HVAC optimization, building energy-management systems, and sustainability platforms can help organizations manage energy consumption and support corporate decarbonization objectives.
IoT and connected assets: Rapid proliferation of IoT sensors, edge devices, and cloud-based analytics enables real-time monitoring and centralized control. This allows building operators to transition from reactive facility management toward proactive and predictive operations.
Urbanization and infrastructure investment: Accelerating urbanization and infrastructure development are creating greenfield and retrofit opportunities, particularly across Asia-Pacific. Government-backed digitalization programs can further encourage intelligent building deployments.
Occupant health, safety, and comfort: Growing attention to occupant well-being is driving investment in integrated platforms that combine access control, air-quality monitoring, emergency communications, occupancy intelligence, space optimization, and security management.
5G and cloud convergence: The growing convergence of 5G connectivity, cloud-based building-management systems, and mobile credentials can lower integration complexity and enable scalable remote management. This creates opportunities for smart-building providers targeting distributed and mid-market commercial properties.
Growth Restraints: Smart Building Solutions Market
The Smart Building Solutions Market faces several barriers that can influence deployment timelines and adoption rates.
High upfront investment: Smart-building deployments can require substantial capital expenditure across sensors, gateways, building-management software, cybersecurity, integration, and related infrastructure. These costs can be particularly challenging for small and medium-sized building owners operating in cost-sensitive markets.
Fragmented technology environments: Buildings often contain systems from multiple vendors, resulting in interoperability and integration challenges. Legacy building-management systems, devices, and software platforms can increase implementation complexity, project timelines, and deployment costs.
Cybersecurity and data privacy: Increasing building connectivity creates additional cybersecurity exposure. Connected buildings can contain sensitive operational, occupant, access, and infrastructure data, requiring organizations to strengthen cybersecurity controls and compliance processes.
Skills shortages: The deployment and management of advanced smart-building environments require skilled professionals, including building-management specialists, IoT engineers, cybersecurity experts, data specialists, and systems integrators. Shortages of qualified personnel can constrain implementation capacity.
Complex project integration: Integrating existing building infrastructure with modern cloud, AI, IoT, and asset-management platforms can require substantial technical expertise. These challenges may delay adoption where building owners lack internal capabilities or appropriate technology partners.
Competitive Landscape: Smart Building Solutions Market
The global Smart Building Solutions Market has a broad competitive ecosystem, with more than 350 companies generating over $5 million in revenue. The competitive environment includes established building-automation providers, energy-management companies, software vendors, technology companies, and specialized smart-building solution providers.
The research identifies Siemens, Schneider Electric, Honeywell, Johnson Controls, Carrier, ABB, Azbil, Acuity, Planon, Spacewell, Trane, and Bosch among the leading competitors. Other notable participants include 75F, Bueno, Delta Controls, Lynxspring, Enlite, Encycle, Facilio, VergeSense, and JLL.
The top four competitors accounted for 74.4% of 2025 revenue, indicating a significant concentration among leading vendors despite the presence of a much broader competitive base.
Key competitive factors include price, flexible payment models, interoperability, AI capabilities, and unified platforms. These factors reflect the industry's transition from individual building-control products toward integrated platforms capable of connecting multiple operational functions.
Distribution structures include direct sales, system integrators, energy consultants, utilities, resellers, and marketplaces. Partner ecosystems are increasingly important because the total addressable market encompasses millions of buildings that cannot efficiently be reached through direct sales alone.
The competitive environment is also characterized by acquisitions and strategic investments. The research identifies Siemens' acquisition of Brightly Software in 2022, Schneider Electric's increased ownership of Planon to a controlling 80% stake in 2024, EcoEnergy Insights being rebranded to Carrier Connected Services, Trane's acquisition of BrainBox AI in 2025, and Bosch's acquisition of Paladin Technologies.
Leading providers offer solutions across the three major strategic pillars. Examples identified in the research include ABB Ability, Acuity Atrius, Azbil Intelligent BMS, Bosch Building Technologies, Carrier Abound, Honeywell Forge, Johnson Controls OpenBlue, Planon, Schneider Electric EcoStruxure, Siemens Building X, Spacewell platforms, and Trane autonomous-control solutions.
As the Smart Building Market evolves, competitive differentiation is increasingly shifting toward AI-enabled automation, unified data platforms, interoperability, recurring software models, ecosystem partnerships, predictive asset management, and measurable energy and operational outcomes.
Scope of Analysis
Segmentation
Why is it Increasingly Difficult to Grow?
The Strategic Imperative 8™
The Impact of the Top 3 Strategic Imperatives on the Smart Building Solutions Industry
Competitive Environment
Top Performers and Emerging Innovators
Growth Metrics
Growth Drivers
Growth Restraints
Revenue Forecast
Revenue Forecast by End-User Vertical
Revenue Forecast by Region
Revenue Forecast Analysis
Revenue Share and Analysis
Competitive Environment—Top Performers in Smart Building Solutions
Growth Metrics
Market Snapshot—North America
Growth Metrics
Market Snapshot—Europe
Growth Metrics
Market Snapshot—Asia-Pacific
Growth Metrics
Market Snapshot—Rest of the World
Growth Opportunity 1: Agentic AI-Led Growth in Smart Buildings
Growth Opportunity 3: Cloud-Based BMS and BEMS Opportunities in Small and Medium-Sized Buildings
Benefits and Impacts of Growth Opportunities
Next Steps
List of Exhibits
Legal Disclaimer
Frequently Asked Questions: Smart Building Solutions Market
1. What is the Smart Building Solutions Market?
The Smart Building Solutions Market covers integrated hardware, software, and digital services that enable automation, optimization, and intelligent management of buildings. The scope includes automation controllers, edge and IoT gateways, building-management platforms, energy-management systems, analytics, and associated digital services.
2. What was the size of the Smart Building Solutions Market in 2025?
According to the provided Frost & Sullivan research, the global Smart Building Solutions Market was valued at approximately $20,045.8 million in 2025.
3. What is the forecast for the Smart Building Solutions Market by 2031?
The global Smart Building Market is forecast to reach approximately $41,070.1 million by 2031, increasing from approximately $20,045.8 million in 2025.
4. What is the CAGR of the Smart Building Solutions Market?
The global Smart Building Solutions Market is projected to grow at a compound annual growth rate of approximately 12.7% between 2025 and 2031, according to the provided Frost & Sullivan research.
5. What are the main segments of the Smart Building Solutions Market?
The Smart Building Market is segmented by end-user vertical into commercial, industrial, education, healthcare, data centers, and others. Other building types include high-rise residential buildings, government buildings, airports, sports complexes, cultural buildings, and industrial warehouses.
6. What are the key pillars of the Smart Building Solutions Market?
Frost & Sullivan structures the Smart Building Solutions Market around three strategic pillars: energy efficiency, operational efficiency, and occupant comfort and safety. These pillars encompass energy-management systems, sustainability solutions, digitized asset management, workplace experience, occupancy intelligence, and safety and security management.
7. What technologies are driving the Smart Building Market?
Key technologies supporting the Smart Building Market include IoT sensors, edge computing, cloud platforms, artificial intelligence, building-management systems, energy-management platforms, connected asset-management solutions, and data analytics. These technologies enable real-time monitoring, predictive maintenance, automation, and intelligent building operations.
8. What are the key growth drivers for the Smart Building Solutions Market?
Major growth drivers for the Smart Building Solutions Market include increasing energy-efficiency requirements, enterprise decarbonization mandates, rising energy costs, IoT adoption, AI-driven building intelligence, urbanization, infrastructure investment, and growing requirements for occupant health, safety, comfort, and operational efficiency.
9. Who are the leading companies in the Smart Building Solutions Market?
Leading companies identified in the Smart Building Solutions Market include Siemens, Schneider Electric, Honeywell, Johnson Controls, Carrier, ABB, Azbil, Acuity, Planon, Spacewell, Trane, and Bosch. The research also identifies numerous other technology providers and specialized smart-building companies.
10. What are the major challenges facing the Smart Building Market?
Major challenges affecting the Smart Building Market include high upfront investment, fragmented building systems, interoperability issues, cybersecurity and data privacy concerns, integration complexity, and shortages of skilled professionals. These factors can increase implementation costs and extend deployment timelines, particularly for smaller building owners.
Speak directly with our analytics experts for tailored recommendations.
Recent related Homes and Buildings research
18 Nov 2026 | Global | Market Research
Facility Management Market, Global, 2025–2032
The facility management (FM) sector is experiencing a major transformation due to external forces, changing customer demands, technology innovation, sustainability commitments, and internal constraints. Geopolitical instability, such as inflation, economic uncertainty, and global conflicts, have dis...
16 Nov 2026 | Global | Market Research
Growth Opportunities for LED Lighting, Global, 2026–2031
The global LED lighting market is relatively mature, with growth increasingly driven by retrofit and replacement demand, stricter energy-efficiency mandates, and increased adoption of smart and connected lighting solutions. Valued at $66,925.8 million in 2025, the market is forecast to reach $78,303...
12 Nov 2026 | Global | Market Research
AI Readiness Assessment of Top 100 Companies in the Homes and Buildings Industry, Global, 2025–2031
The analysis assesses AI's influence in the homes and buildings industry, covering both residential and commercial segments.AI applications are segmented into two broad segments: smart homes and smart buildings and infrastructure. They are further segmented into 5 subsegments: digitized maintenance ...
28 Oct 2026 | Global | Market Research
Emerging Software Providers for Smart Building and FM Markets, Global, 2026
Software has become the decisive layer in smart building and facility management, and this study profiles the emerging providers reshaping the global market. It examines how digital platforms are used to monitor, control, analyze, and manage building systems and facility operations across commercial...
22 Oct 2026 | Global | Market Research
Building Construction Market, Global, 2026–2031
The global building construction market is expected to grow steadily from $8.89 trillion in 2025 to $10.56 trillion by 2031, at a 2.9% CAGR, supported by urbanization, housing demand, industrial expansion, and investment in data centers, healthcare facilities, logistics hubs, and advanced manufactur...
Purchase includes:
- Report download
- Growth Dialog™ with our experts
Growth Dialog™
A tailored session with you where we identify the:- Strategic Imperatives
- Growth Opportunities
- Best Practices
- Companies to Action
Impacting your company's future growth potential.