 USD
 GBP
 CNY
 EUR
 INR
 JPY
 MYR
 ZAR
 KRW
 THB


Growth Potential Enhanced by 4-layered Platform Approach Toward CASE
23-Sep-2020
Global
Market Research
MF26-01-00-00-00
AU02004-GL-MR_24447
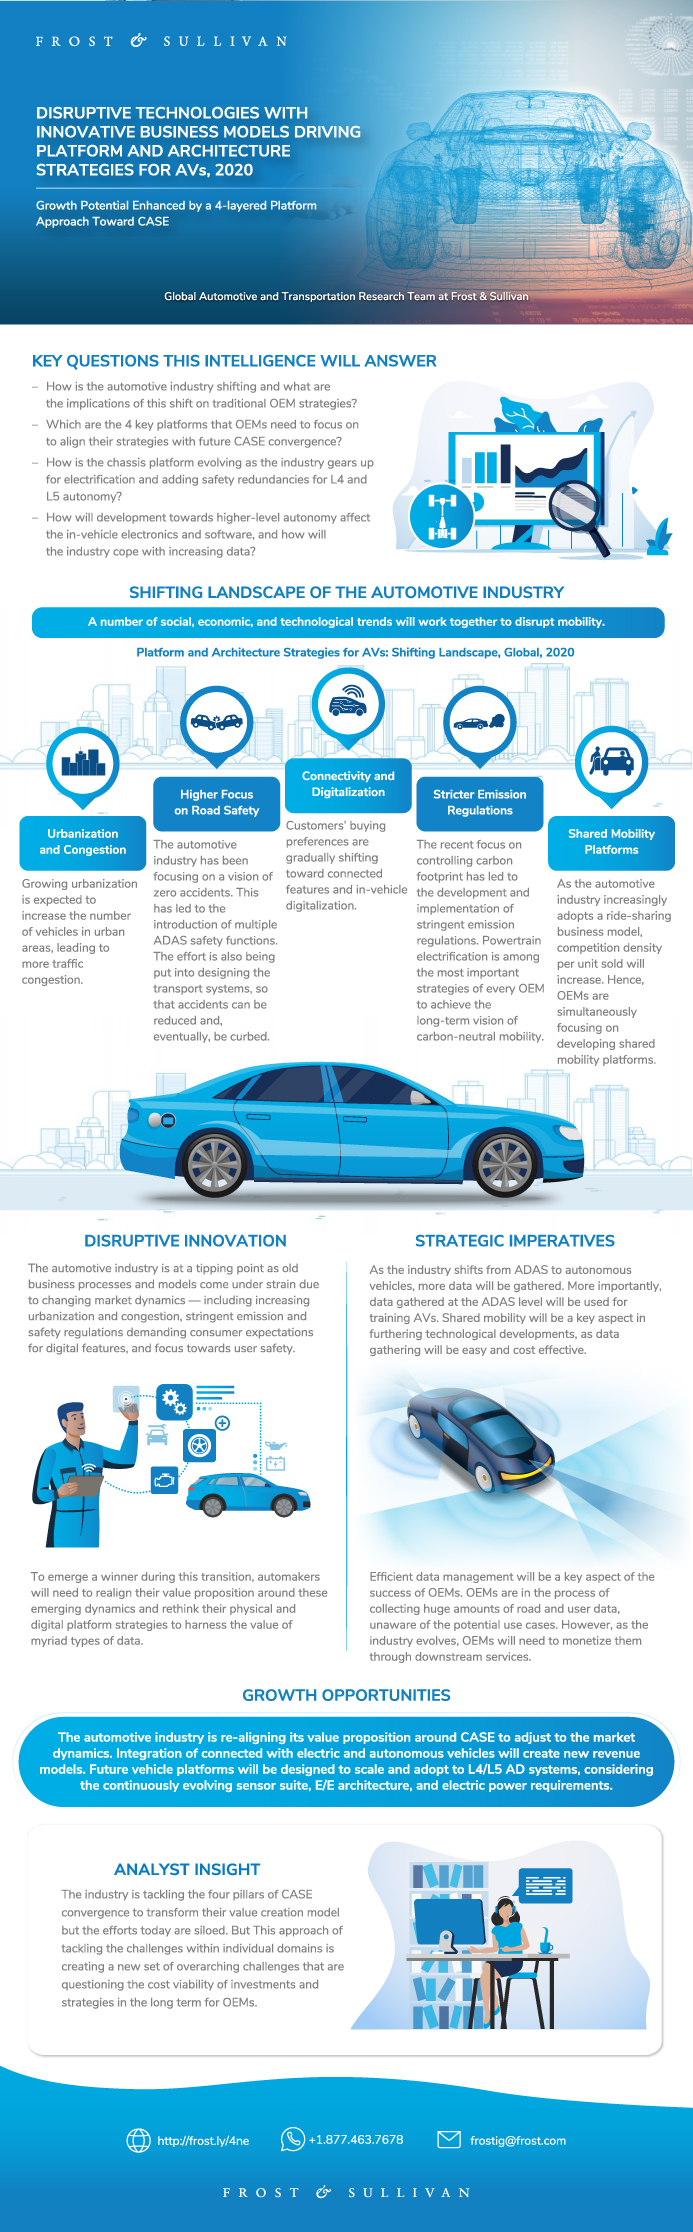
The automotive industry is at a tipping point, with traditional business models being disrupted, changing the market dynamics?increasing urbanization and congestion, tighter emission and safety regulations, evolving consumer expectations for digital features, and focus on user safety. The ecosystem is evolving at a rapid pace, not only through the emergence of new business models, but also on the technological front.
Traditionally, most OEMs and Tier-I suppliers have been taking the siloed approach for developments in connected, autonomous, and electric vehicles. However, this approach of singular focus is not viable for the long term. OEMs will need strategies that explore the benefits of developing applications focused on the convergence of the 3 technology pillars. To cope with this transition, automakers will need to realign their value proposition around these emerging dynamics and rethink their physical and digital platform strategies to harness the value of myriad types of data.
Powertrain electrification is among the most important strategies of every OEM to achieve the long-term vision of carbon-neutral mobility. OEMs are also aiming to create a consolidated chassis platform, which will be modular enough to handle multiple segments of vehicles. These factors will force the OEMs to shift from well-established legacy chassis platforms to multi-energy platforms (MEPs) and modular and dedicated electric platforms. OEMs are also focused on strengthening their E/E architecture, which can handle humongous data sizes from continuously evolving sensor suite and processing software. The rise of data ingestion per vehicle has called in the significance of cloud computation as on-premise servers become incapable.
The study covers the key platforms that OEMs need to focus on, as they shift their strategy to data-centric revenue models from traditional vehicle-centric business models. As every OEM strategizes their individual path toward CASE convergence, the expected evolution of the platforms are explored, along with major industry partnerships.
Key Issues Addressed
- How is the automotive industry shifting, and what are the implications of that shift on traditional OEM strategies?
- Which are the 4 key platforms that OEMs need to focus on to align their strategy with future CASE convergence?
- How is the chassis platform evolving, as the industry gears up for electrification and adding redundancies for L4 and L5 autonomy?
- How will development toward higher-level autonomy affect the in-vehicle electronics and software, and how will the industry cope with increasing data?
- What are specific OEMs and developers strategizing for the 4 key platforms?
Platform Components
Chassis Platform
Electronic Platform
Software Platform
Cloud Platform
Partnership Strategies across Platforms
Key Conclusions
Research Scope
Key Questions this Study will Answer
Vehicle Segmentation
Standards for Autonomous Driving
Electric Vehicle (xEV) in Scope
Shifting Landscape of the Automotive Industry
Industry Optimizations Due to Shifting Landscape
Key Challenges for OEMs with Traditional Development
Platform-based Approach Toward CASE
Future Autonomous Vehicle Platforms
Modular and Skateboard Platforms
Key Platforms
OEMs’ Strategy—BEVs on Skateboard Platform
Evolution of E/E Architecture
Evolution of Sensor Hardware
Role of Sensor Data Fusion by Level of Automation
EV Power Components
OEM E/E Architecture Strategies
EV Battery and Motor Strategy
Key In-vehicle Software Enabling AD
Software-Hardware Decoupling
AI-based Software Vs. Conventional Software
Role of Machine Learning
Implementation of Machine Learning
Autonomous Driving Software Platforms
Data Storage and Computing for AVs
Edge Vs. Cloud Computing
Cloud-Edge Computation Models
Cloud Storage and Computation
OEM Cloud Strategy
CASE Convergence
Implications of CASE Convergence
Growth Opportunity—Investments and Partnerships from OEMs/TSPs
Strategic Imperatives for Success and Growth
Key Conclusions
The Last Word—3 Big Predictions
Legal Disclaimer
Market Engineering Methodology
Abbreviations and Acronyms Used
List of Exhibits
List of Exhibits (continued)
List of Exhibits (continued)
Speak directly with our analytics experts for tailored recommendations.
Recent related Automotive research
16 Sep 2026 | North America | Customer Research
US Automotive Technicians’ Choice Survey, 2025
The 2025 US Automotive Technicians’ Choice study is an insightful voice-of-customer survey that highlights the tool preferences of automotive aftermarket service technicians. The survey of 400 automotive technicians across the United States used a combination of computer-assisted telephone and compu...
10 Sep 2026 | Global | Market Research
Global Robobus Market, 2026–2032
The global robobus market is at an inflection point. Large autonomous buses are no longer a concept—they are running as paid public services in China, South Korea, Norway, Switzerland, Finland, and the Netherlands. Europe is in its first wave of real deployment, with active L4 commercial service acr...
03 Sep 2026 | Global | Technology Research
Photonic and Optical Computing Chips for AI and Data Center Acceleration
The study evaluates photonic and optical computing technologies as critical enablers of next-generation AI infrastructure, addressing growing bandwidth, latency, power consumption, and scalability constraints associated with copper-based interconnects. The analysis covers photonic integrated circuit...
02 Sep 2026 | Global | Frost Radar
Frost Radar™: In-Vehicle Audio Technology Stacks, 2026
The in-vehicle entertainment industry is going through a dynamic shift. Audio entertainment in the passenger vehicle is no longer limited to music playback through multiple sources. The rise of ADAS/AD and SDVs have made audio a critical part of the passenger vehicle. Audio developers must now cater...
31 Aug 2026 | Global | Market Outlook
Off-Highway Equipment Market Predictions and Growth Opportunities, Global, 2026
The global off-highway (OHW) equipment industry enters 2026 amid a complex and evolving macroeconomic environment characterized by geopolitical uncertainty, energy price volatility, and shifting trade dynamics. While the baseline outlook suggests moderate global GDP growth of about 3%, downside scen...
Purchase includes:
- Report download
- Growth Dialog™ with our experts
Growth Dialog™
A tailored session with you where we identify the:- Strategic Imperatives
- Growth Opportunities
- Best Practices
- Companies to Action
Impacting your company's future growth potential.
Key Issues Addressed
- How is the automotive industry shifting, and what are the implications of that shift on traditional OEM strategies?
- Which are the 4 key platforms that OEMs need to focus on to align their strategy with future CASE convergence?
- How is the chassis platform evolving, as the industry gears up for electrification and adding redundancies for L4 and L5 autonomy?
- How will development toward higher-level autonomy affect the in-vehicle electronics and software, and how will the industry cope with increasing data?
- What are specific OEMs and developers strategizing for the 4 key platforms?
| Deliverable Type | Market Research |
|---|---|
| No Index | No |
| Podcast | No |
| Author | Ayan Biswas |
| Industries | Automotive |
| WIP Number | MF26-01-00-00-00 |
| Is Prebook | No |
| GPS Codes | 9800-A6,9882-A6,9B13-A6 |
Disruptive Technologies with Innovative Business Models Driving Platform and Architecture Strategies for AVs, 2020
$4,950.00
Special Price $3,712.50 save 25 %