 USD
 GBP
 CNY
 EUR
 INR
 JPY
 MYR
 ZAR
 KRW
 THB


Preparing for the Rebound
The global defence spending was recorded at $1.8 trillion in 2018; the highest spending recorded, to date. The COVID-19 epidemic is likely to reduce defence spending as governments around the world allocate funds for both fighting the pandemic and reviving the economy. COVID-19 is a dual crisis—public health and economic downturn—unlike any other preceding financial or health crisis. Stresses in the financial system led to the Global Financial Crisis of 2008 and the collapse of the stock market, followed by a decrease in demand due to lower per capita income. The Dotcom burst was led by a collapse of the stock market.
Previous health emergencies, such as the outbreak of SARS or EBOLA, were limited in their geographical scope and the consequent effect on the world economy. COVID-19 is a supply-chain-led shock due to lockdown measures, which portends the winding down of businesses with consequent spill over onto demand and the financial system. The underlying demand and economy were healthy before the start of the crisis. Therefore, the restoration of supply and economy will depend on how quickly the disease is contained.
Examination of previous trends has shown that defence spending is a function of political uncertainty, GDP growth, and budget deficits, with political tension emerging as the dominant factor. Frost & Sullivan estimates that political uncertainty will increase due to attempts at political isolation of China which is being blamed for giving incorrect information on the true nature of the infection. This would be compounded by the actions of Russia and North Korea which seek to take advantage of the geopolitical chaos. In the near term (2020-2021), Frost & Sullivan estimates that the defence spending will stagnate or dip slightly, subject to political factors; however, in the long term, the defence spending is likely to go down by at least 10% as seen in the past.
This report will further investigate the effects of the crisis and its impact on the economy and defence spending, breaking down what will potentially happen into scenarios. Furthermore, the virus has had the biggest impact on global defence supply chains, which will be investigated in greater detail, such as a risk of greater supply chain solvency. A future outlook is provided, whereby an overview of the defence industry for the next 6 to12 months is discussed. Most importantly, the report will analyse six growth opportunities that will emerge from the crisis for companies to investigate and follow.
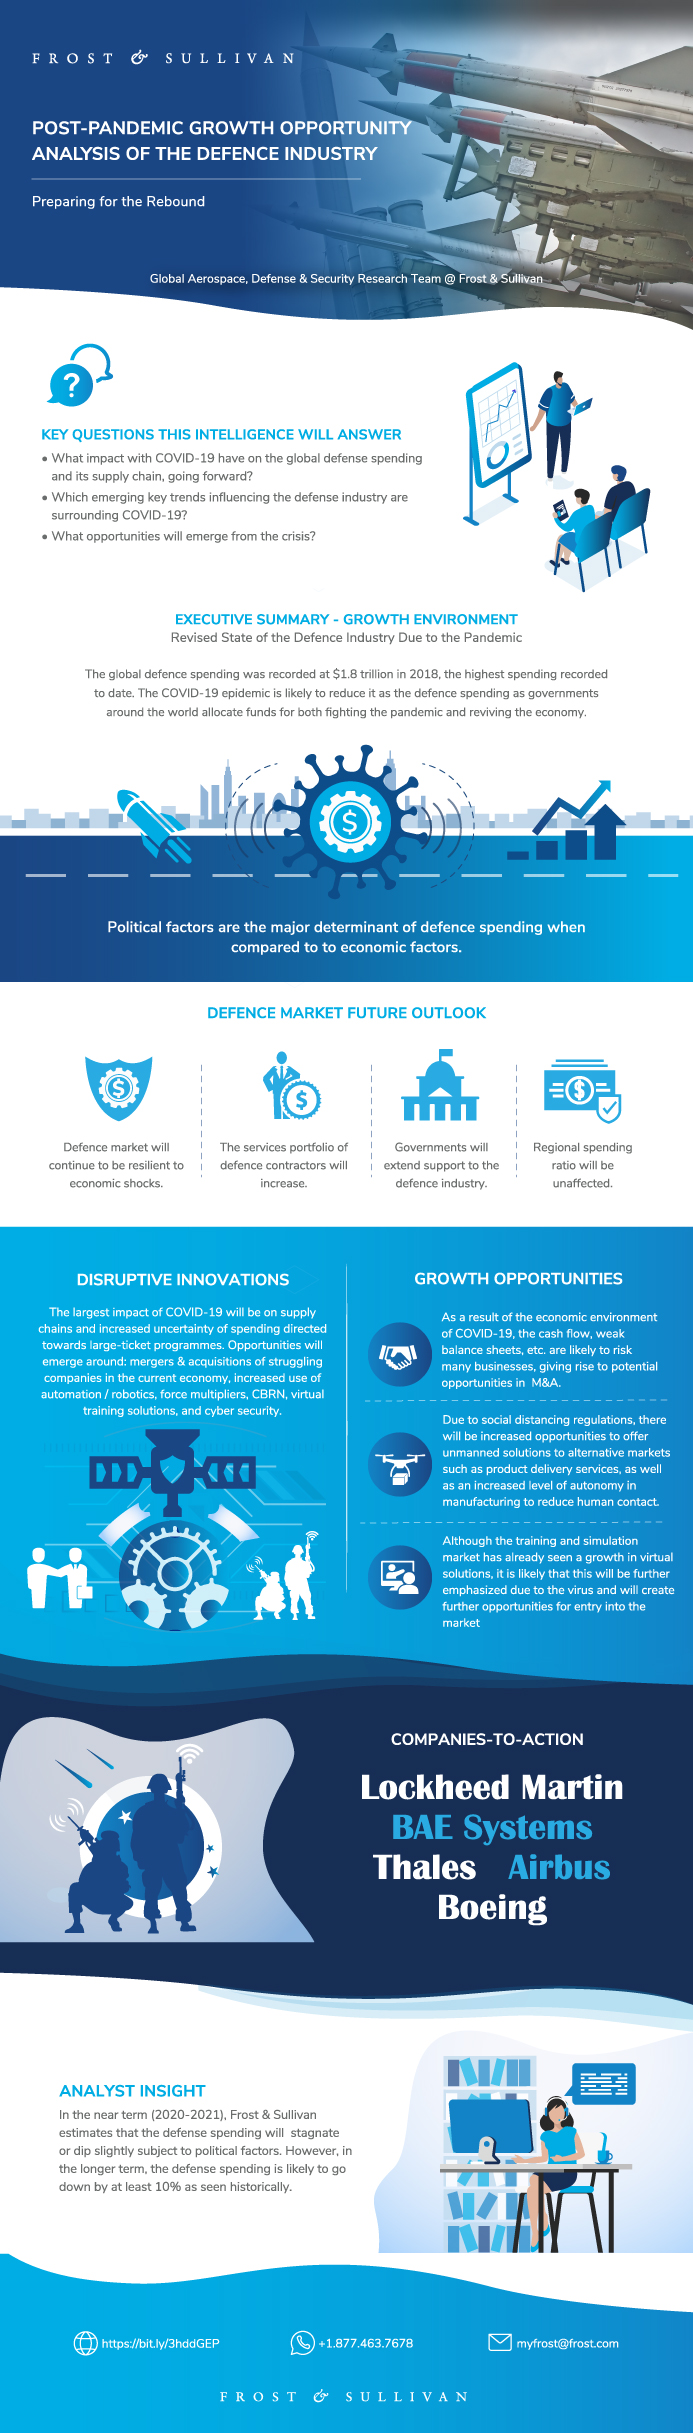
Revised State of the Defence Industry Due to the Pandemic
Key Forecast Criteria
GDP Forecast
Defence Spending: Global Historical Trend
Defence Spending: Regional Historical Trend
Discussion of Defence Spending Trends
Geopolitics Over GDP: Driving Defence Spending
Discussion of Geopolitical Factors
Discussion of Geopolitical Factors (continued)
Discussion of Geopolitical Factors (continued)
Top 15 Defence Spenders Dashboard
Summary: Impact on Defence Spending
Impact on Supply Chain
Long Term Impacts On Defence Industry
Other Forecast Trends
Defence Market Future Outlook
Growth Opportunity 1: Mergers & Acquisitions for Portfolio Consolidation, 2020
Growth Opportunity 2: Vertical Integration for Lower Costs and Aftermarket Capture, 2020
Growth Opportunity 3: Robotics & AI for Leaner Operations,2020
Growth Opportunity 4: Force Multipliers for Enhanced Operational Effectiveness, 2020
Growth Opportunity 5: CBRN for Quicker Disaster Response, 2020
Growth Opportunity 6: Training and Simulation for Virtual Learning Environment, 2020
Companies to Action
About the Growth Pipeline Engine™
Next Steps
Legal Disclaimer
Speak directly with our analytics experts for tailored recommendations.
Recent related industry research
17 Sep 2026 | Asia Pacific | Frost Radar
Frost Radar™: Facility Management in Malaysia, 2026
Malaysia's facility management (FM) market is transitioning from labor-intensive, compliance-driven service delivery to technology-enabled, outcome-oriented, and sustainability-integrated operating models. Competitive differentiation increasingly depends on providers’ ability to combine integrated F...
17 Sep 2026 | Global | Market Research
Growth Opportunities in the Western Europe Consumer eSIM Market, 2026–2029
The consumer eSIM market in Western Europe is growing steadily, supported by the rising availability of eSIM-capable devices, particularly smartphones, and expanding travel-related use cases. However, commercialization has yet to translate into mass adoption. Despite Apple’s global launch of an eSIM...
17 Sep 2026 | Asia Pacific | Frost Radar
Frost Radar™: ASEAN Warehouse Automation System Providers, 2026
Warehouse automation has moved from a discretionary capital project to a core operating capability. ASEAN operators are redesigning fulfillment networks around smaller orders, shorter delivery windows, broader stock keeping unit (SKU) ranges, and sharper demand volatility. Manual operations remain v...
16 Sep 2026 | North America | Customer Research
US Automotive Technicians’ Choice Survey, 2025
The 2025 US Automotive Technicians’ Choice study is an insightful voice-of-customer survey that highlights the tool preferences of automotive aftermarket service technicians. The survey of 400 automotive technicians across the United States used a combination of computer-assisted telephone and compu...
16 Sep 2026 | Global | Market Research
Apple Performance Tracker, Q1 2026
This Frost & Sullivan tracker provides metrics on Apple's quarterly performance (for both unit sales and revenues) for iPads, iPhones, Macs, and other products, such as iPods, Apple TVs, Beats Electronics, and Apple-branded and third-party accessories. It includes historical quarterly data for all t...
Purchase includes:
- Report download
- Growth Dialog™ with our experts
Growth Dialog™
A tailored session with you where we identify the:- Strategic Imperatives
- Growth Opportunities
- Best Practices
- Companies to Action
Impacting your company's future growth potential.
| Deliverable Type | Market Outlook |
|---|---|
| No Index | No |
| Podcast | No |
| Author | Alexander Clark |
| Industries | Aerospace, Defence and Security |
| WIP Number | MF75-01-00-00-00 |
| Is Prebook | No |
| GPS Codes | 9000-A1 |